Instant Cash Advance: Loan App

Screenshots
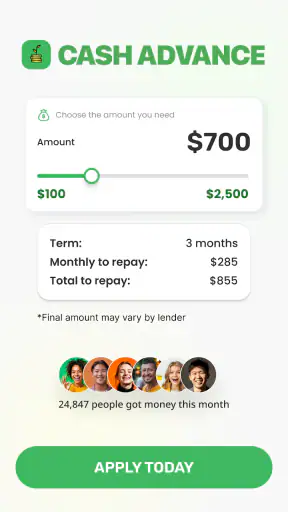
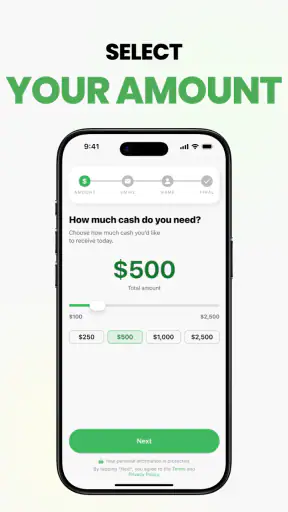
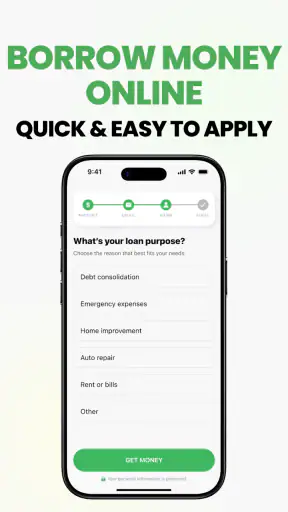
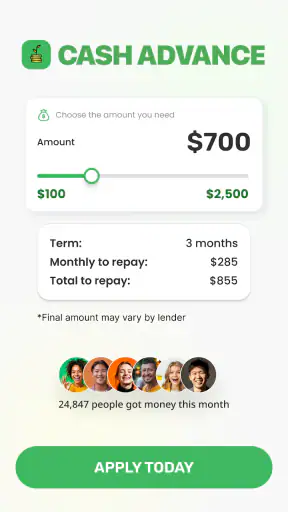
Details
- Rating
- 235.00 reviews
- Version
- 2.0.7
- Developer
- Smart Finance Club
Analysis by Norviv
When I look at a finance app that promises fast access to cash, I pay less attention to the speed claim and more attention to the points where a real person can get stuck. Instant Cash Advance: Loan App, from Smart Finance Club, is built around a short application journey for people looking for an advance, but a short journey does not always mean a simple decision. The important questions are whether you can complete the process comfortably, understand what you are agreeing to, and recover sensibly if something interrupts the application.
My overall impression is that this is a focused borrowing tool rather than a general money-management app. It does not try to replace budgeting, savings, banking, or bill-tracking software. Its purpose is narrower: help a user begin a cash-advance request through a mobile interface. That makes it potentially useful during a temporary cash gap, but it also means I would approach it with more caution than I would a calculator or expense tracker.
The app is free to install, carries an Everyone age rating, and supports Android devices running version 7.0 or later. It was released on April 6, 2021, and the current version is 2.0.7. Its average rating is 3.8 from around 3.2 thousand ratings, with over 100 thousand installs. Those figures suggest that people are trying it, while the less-than-excellent rating is a useful reminder to keep expectations realistic and inspect every step instead of assuming that “instant” means guaranteed.
Where the cash-advance process can become difficult
The first point of friction is usually not tapping through the application. It is deciding whether an advance is appropriate in the first place. If the money is needed for a one-off timing problem, such as covering an essential expense before regular income arrives, a short-term option may feel practical. If the same shortage happens every pay cycle, borrowing can simply move the pressure forward. I would use this app only after writing down the amount needed and the date on which repayment would be manageable.
A second sticking point is the difference between starting an application and receiving money. A mobile form can make the first part feel quick, but approval, eligibility, verification, and transfer are separate matters. I would not plan a rent payment, utility cutoff, medical purchase, or other deadline around an assumption that an application will automatically produce funds. The app can be a way to request an advance; it should not be treated as a promise of approval or timing.
Users can also get frustrated when they expect a single button to solve everything. Finance applications often depend on accurate personal and financial details, and a mismatch can slow the process. A mistyped name, outdated contact detail, incorrect income information, or incomplete response may create more trouble than the app itself. My practical advice is to prepare the information before opening the form rather than rushing through it on a small screen.
There is another kind of friction that is easy to overlook: the emotional pressure of needing money quickly. When a person is anxious, it is tempting to accept the first available option without reading carefully. I would pause at every screen involving repayment, fees, authorization, or consent. A fast interface is helpful, but it should never replace a slow reading of the financial obligation.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What I would check before starting
Before using the app, I would confirm that the device is compatible and that the application is updated to the current version shown in the app listing. Since it supports Android 7.0 and newer, older phones may be the first thing to check if installation or opening fails. I would also make sure there is enough free storage, a stable connection, and a battery level high enough to finish the process without interruption.
I would use a reliable connection rather than switching repeatedly between mobile data and Wi-Fi. A network change at the exact moment a form is submitted can make a completed step appear unsuccessful. If the app seems frozen, I would wait briefly before pressing the submission control again. Repeated taps can create confusion about whether a request was sent once or more than once.
Account details deserve the same care as the technical setup. I would enter information exactly as it appears on the relevant documents and avoid using an unfamiliar device if privacy is a concern. I would not share verification codes, passwords, or sensitive financial details with another person claiming to assist. The app is a finance product, so basic account security matters more here than it does in an ordinary entertainment download.
Reading the full offer is the most important setup check. I would look for the total repayment amount, the repayment date, any applicable charges, and the consequences of missing that date. The store summary describes a three-step cash-advance process, but the number of steps should not be mistaken for a complete explanation of the financial terms. The useful question is not merely “Can I apply quickly?” but “Can I repay the full obligation without creating another emergency?”
I would also decide in advance what I will do if the request is not accepted or takes longer than expected. That might mean contacting the bill provider, asking for a payment arrangement, using an existing emergency fund, or speaking with a trusted financial adviser. Having a backup plan reduces the chance of making a rushed second borrowing decision while waiting for the first one.
How I would work through an interrupted application
If the process stops halfway, I would first note the exact screen or message rather than immediately uninstalling the app. A simple restart may resolve a temporary loading problem, but I would avoid clearing information or deleting the app until I know whether that could remove progress. I would close other demanding apps, reopen the loan app, and try again on a steady connection.
If a button appears unresponsive, I would check whether a required field has been left blank or whether the keyboard is covering a warning near the bottom of the screen. Small displays can hide validation messages, especially when a form scrolls. Rotating the phone is not always appropriate during a financial application, so I would instead scroll carefully and review each section from top to bottom.
When a submission seems to fail, I would check for a confirmation message, notification, email, or application status before starting over. The safest recovery habit is to avoid duplicate requests created by impatience. If the app shows no clear status, I would record the time of the attempt and use the official support route associated with the service rather than searching for unofficial contacts.
Connection problems are another common source of apparent failure. I would test whether another ordinary website or app loads, then retry only after the connection is stable. If everything else works but this application continues to fail, the issue may be temporary service availability or an account-specific problem. In that situation, repeated attempts are unlikely to improve the result and may make the history harder to understand.
For an application that closes unexpectedly, I would restart the phone and check that the operating system and app are not unusually outdated. I would be cautious about installing random “fix” tools or modified versions, because a finance app is not a place to experiment with unofficial software. If the problem continues, I would save the wording of any error and contact the developer, Smart Finance Club, through the legitimate channel connected with the app.
When the application is not the real problem
Sometimes the difficulty is caused by eligibility, identity information, or repayment capacity rather than a technical defect. A request can be delayed because details do not match, because the service needs additional checks, or because the user does not meet the relevant conditions. Since those decisions are not something a phone restart can solve, I would avoid treating every unsuccessful outcome as an app bug.
The same applies to transfer timing. Even if the application screen completes normally, banking systems and account details can affect when money becomes available. I would verify that the destination information is correct and avoid relying on an advance for a deadline that cannot move. If the money is needed immediately for a critical expense, speaking directly with the recipient or provider may be more dependable than waiting silently.
Repayment trouble is also a planning issue, not merely an interface issue. Before accepting anything, I would compare the full repayment with my next income and existing commitments. An advance that solves today’s shortage but causes an overdraft, missed bill, or second loan later may be poor value even if the application itself works perfectly.
This is where the app differs from the usual alternatives in the finance category. A budgeting app helps identify why money is short and where spending can be adjusted. A bank’s own overdraft or credit facility may provide clearer integration with an existing account, while an employer-linked wage-access service may suit someone whose workplace supports it. A community credit union or a direct conversation with a bill provider can sometimes offer a more sustainable answer. I would compare those paths before choosing a short-term advance.
Small habits that make the experience safer
One useful habit is to create a written “borrow only” figure before opening the app. I would exclude optional spending and request no more than the amount tied to the immediate need. This prevents the available application flow from quietly becoming a reason to borrow extra. It also makes the repayment calculation easier to judge.
Another is to take private notes of the terms before confirming, without storing sensitive information in an exposed place. I would record the repayment date and total amount in a secure personal reminder. That is especially valuable if the app is later closed, updated, or unavailable when I need to check what I agreed to.
I would also separate troubleshooting from decision-making. If the app is slow, I would solve the connection or device issue first, then return to the financial terms with a clear head. Combining technical frustration with money pressure is a poor environment for accepting an obligation. This two-stage approach is one of the simplest ways to avoid an accidental decision.
Finally, I would treat the free download as only the entry cost, not the cost of borrowing. The installation price tells me that I can try the app without paying for the download, but it says nothing by itself about the price of an advance. The meaningful comparison is the complete repayment obligation against other available options.
Who should use it, and who should skip it?
I can see this app being useful for an Android user who has a temporary, clearly defined cash gap, understands the repayment commitment, and wants to begin the process from a phone. It may also suit someone who prefers a focused application instead of visiting a branch or navigating a broader banking app. The short, three-step structure can feel less intimidating when the user has already prepared the necessary information.
I would skip it if I needed a guaranteed emergency payment, if repayment would depend on another loan, or if I was unsure about the total cost. I would also look elsewhere if I wanted ongoing budgeting tools, spending analysis, savings goals, or a complete view of my accounts. This is not the right category of product for those jobs.
People who are uncomfortable entering financial information on a mobile device should not feel pressured to use it simply because the process is advertised as fast. A bank, credit union, trusted adviser, or direct conversation with a creditor may provide a better experience. Likewise, anyone using an unsupported or very old Android device should resolve compatibility concerns before making the app part of an urgent plan.
My practical verdict
After considering how it fits into real use, I see Instant Cash Advance: Loan App as a narrowly focused option for beginning a cash-advance request, not as a complete solution to financial stress. Smart Finance Club has kept the stated journey compact, and the free availability makes it easy to access on compatible Android phones. Its presence on more than 100 thousand devices shows that it has reached a meaningful audience, but the 3.8 average tells me to balance convenience with careful checking.
The strongest reason to try it is a specific short-term need combined with a realistic repayment plan. The strongest reason to avoid it is uncertainty: uncertainty about the amount required, the repayment date, the total obligation, or what will happen if the request is delayed. In those situations, a budgeting tool, an existing bank option, a credit union, or a negotiated payment arrangement may be more appropriate.
My recommendation is therefore conditional rather than enthusiastic. Install it only from a legitimate source, check device compatibility, use accurate information, read every financial term, and keep a backup plan. The app may simplify the application, but it cannot make borrowing risk-free. Used with that understanding, it can be a practical starting point for some Android users; used in panic or without a repayment plan, it is probably the wrong tool.
Frequently Asked Questions
01What is Instant Cash Advance: Loan App?
Instant Cash Advance: Loan App is a financial service application designed to help eligible users request short-term cash advances or personal loans from a mobile device. After creating an account and providing the requested information, users may receive an eligibility decision and, if approved, funds according to the provider’s terms. It is not a guaranteed source of money, and availability, loan amounts, and approval requirements can vary by location and individual circumstances.
02How does the application work, and what information is required?
After installing the app, you generally need to register with personal details, verify your identity, and provide information about your income, employment, banking account, or other financial circumstances. The app uses this information to assess eligibility and present available options. Before accepting an offer, carefully review the repayment schedule, interest rate, fees, due date, and total repayment amount. Only submit accurate information and use an official, secure version of the app.
03How much does borrowing through the app cost?
The cost depends on the specific offer, your location, credit profile, loan amount, and repayment period. Possible charges may include interest, origination fees, service fees, late-payment fees, or other costs disclosed in the agreement. An advertised advance may appear inexpensive, but short repayment periods can make the effective cost high. Read all disclosures before confirming, compare alternatives, and make sure you understand the total amount that will be withdrawn or repaid.
04How quickly can I receive the money after approval?
The app may advertise rapid decisions or same-day funding, but timing is not guaranteed. Approval can depend on identity verification, application reviews, banking hours, weekends, holidays, and the receiving bank’s processing speed. Some users may receive funds quickly, while others may experience delays or be declined. The app should not be treated as an emergency guarantee, so check the expected delivery time and any transfer fee before accepting an offer.
05Is Instant Cash Advance: Loan App safe to use?
Before downloading or submitting financial information, verify that the app is published by the legitimate provider and review its privacy policy, permissions, ratings, and user feedback. Avoid applications that request unnecessary access to contacts, photos, or messages, or that promise approval without checking eligibility. Never pay an upfront fee to unlock a loan unless it is clearly explained in official documentation. Also confirm the lender’s licensing and consumer-protection requirements in your country or state.


